
Planning a wedding involves significant upfront spending on venues, decorators, caterers, and travel. When unexpected crises strike like sudden venue unavailability, vendor defaults, or extreme weather families risk losing massive non-refundable deposits. While wedding insurance offers a crucial financial safety net against such disruptions, it is not a blanket guarantee for every mishap. Coverage strictly depends on specific policy terms, claim limits, and exclusions. Before signing on the dotted line, couples must understand these essential rules to protect their celebration funds effectively.
A venue backing out does not automatically guarantee an insurance payout. As wedding planner Pratik Sheth notes, policies treat cancellations from fires or natural disasters differently than commercial disputes, making it essential to verify exact triggers for postponement and relocation. (Image: Canva)
If your decorator or caterer fails to show up, your financial loss might not be reimbursed. Wedding planner Nikita Dubey advises confirming whether vendor failure is explicitly covered, checking required proof, and reviewing the venue’s own refund terms separately. (Image: Canva)
Never assume rain, storms, or extreme heat are automatically covered for outdoor celebrations. Couples must declare whether functions use indoor halls or temporary setups like mandaps and stages, and verify coverage limits for damaged wedding attire and rented equipment. (Image: Canva)
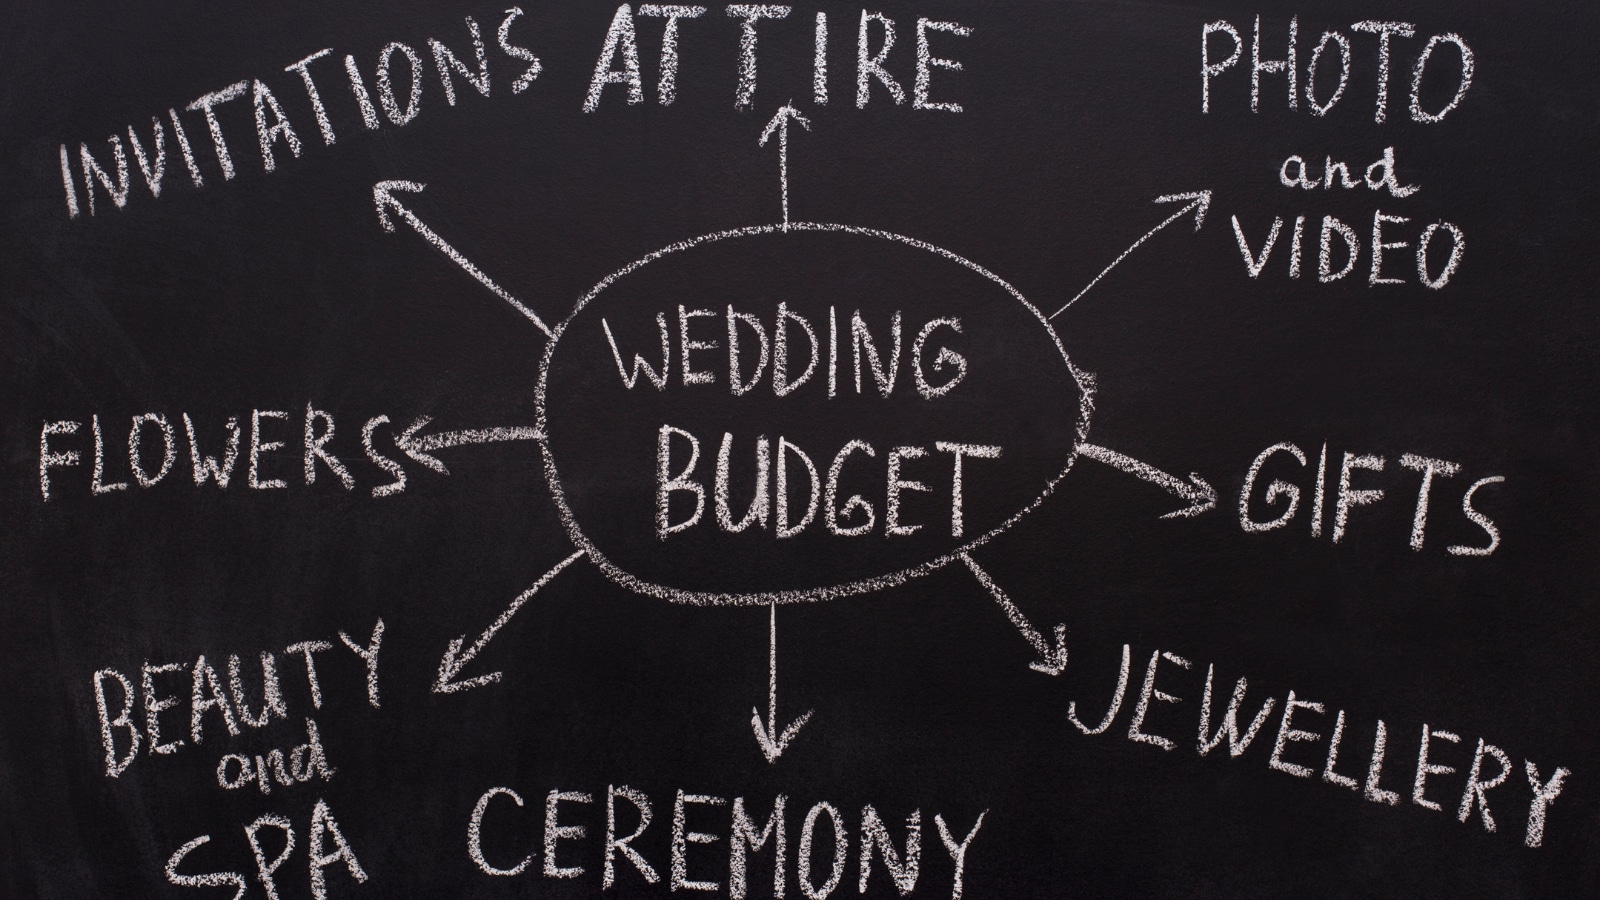
Instead of insuring your total wedding budget, calculate the exact money you could lose if plans collapse. Review contracts and deposit receipts to total up non-refundable advances, while verifying if destination costs like guest hotels and transport are included. (Image: Canva)
Insurance policies come with deductibles, strict claim limits, and exclusions—meaning last-minute upgrades or contractual penalties often come out of pocket. Combining proper insurance with airtight vendor contracts and a dedicated cash reserve protects you while claims undergo assessment. (Image: Canva)
Do not pick a policy based on a cheap premium alone. Check the insurer’s legal name, product Unique Identification Number (UIN), claim filing deadlines, and whether previously paid advances are protected before finalizing your written proposal. (Image: Canva)
Wedding policies rarely cover guest travel hiccups. As insurance expert Gurmeet Singh highlights, families hosting destination weddings should buy separate travel insurance to protect against overseas medical emergencies, lost baggage, and flight delays, while carefully checking pre-existing condition rules. (Image: Canva)
Source link
[ad_3]

