
If your salary seems to disappear long before the month ends, the issue might not be your income level, but a lack of spending boundaries. The 50/30/20 budgeting rule offers a practical framework to regain financial control. By organizing your take-home pay into needs, wants, and savings, this flexible guide helps you manage daily expenses while building long-term financial security.
The 50/30/20 rule divides your net take-home salary into three buckets: 50% for essential needs, 30% for lifestyle wants, and 20% for future savings. It serves as a adaptable starting framework rather than a rigid rule. (Image: Canva)
Allocate half of your take-home pay to unavoidable living costs. This includes rent or home loan EMIs, groceries, utilities, basic transportation, insurance premiums, and minimum debt repayments. For a Rs 60,000 monthly income, target keeping needs around Rs 30,000. (Image: Canva)
Set aside 30% for discretionary expenses that enhance life quality, such as dining out, entertainment, hobbies, travel, and subscriptions. Assigning a clear boundary allows you to enjoy life guilt-free while protecting your long-term savings from lifestyle inflation. (Image: Canva)
Direct the final 20% toward long-term financial goals, including emergency funds, retirement planning, and future major purchases. SEBI investor guidelines emphasize saving deliberately right after payday rather than relying on whatever funds remain at month-end. (Image: Canva)
High living costs in major cities may push essential needs beyond 50%. RBI guidelines recognize budgeting as a flexible tool. If needs require 60%, temporarily reduce lifestyle spending instead of abandoning your savings goals entirely. (Image: Canva)
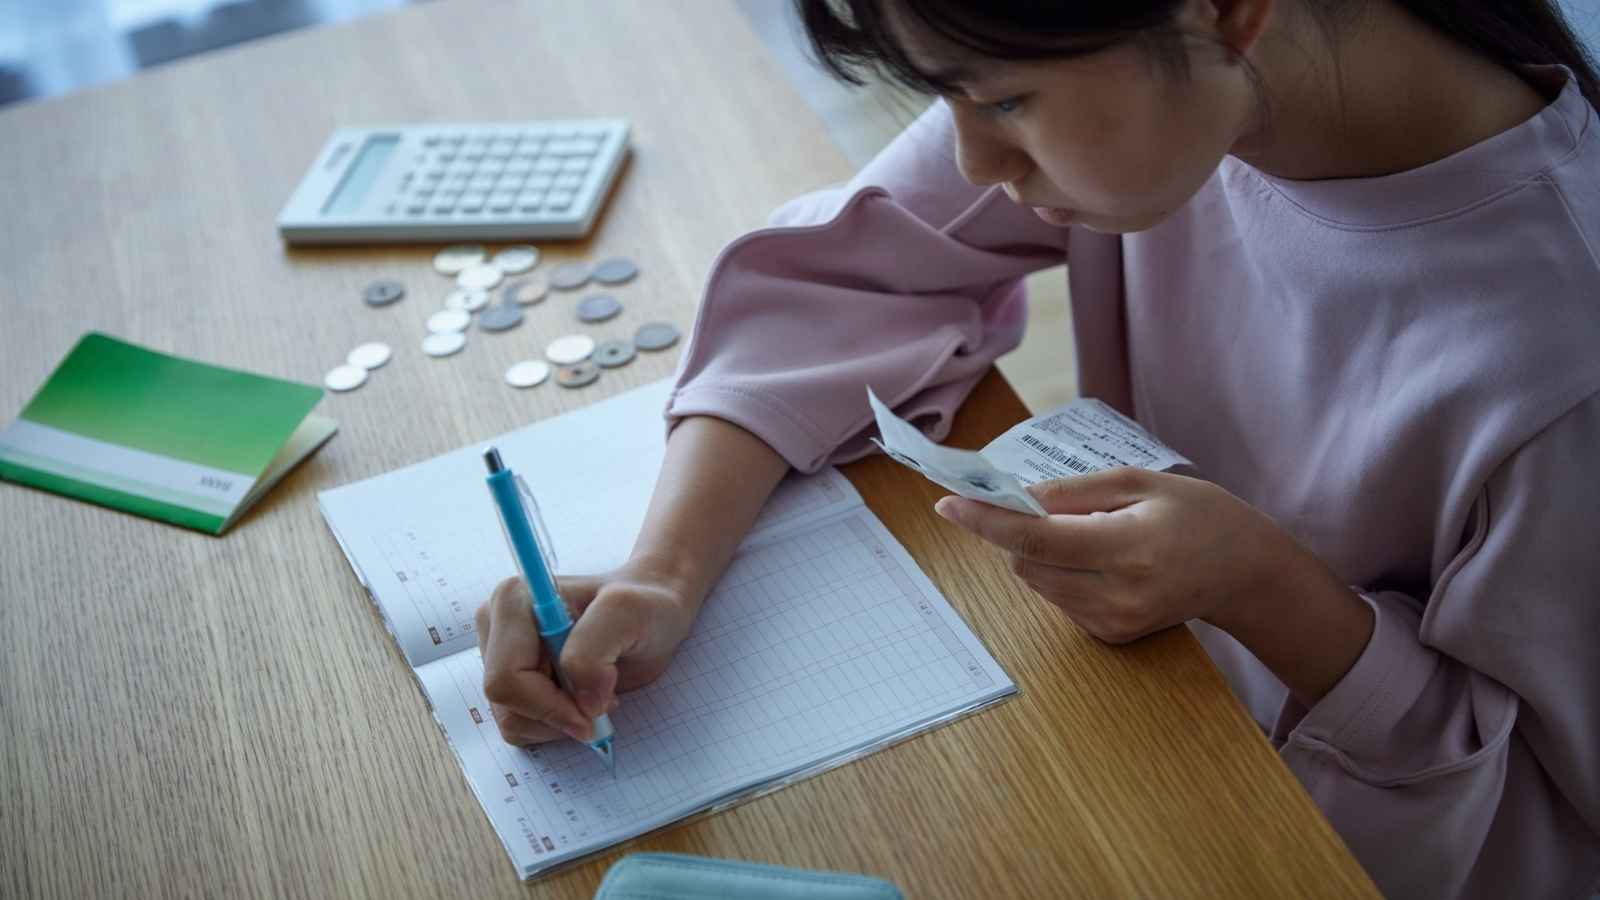
Base your calculations on actual take-home pay rather than gross CTC. Track every expense for at least one month to categorize spending accurately. You may discover hidden costs, such as unused digital subscriptions or discretionary choices mislabeled as needs. (Image: Canva)
Automating your savings transfer immediately upon receiving your salary makes financial discipline effortless. Educational guidelines from NISM highlight the importance of prioritizing essential expenses, setting aside emergency funds, and investing consistently for future financial security. (Canva)
Treat the 50/30/20 method as a benchmark to track cash flow and spot improvement areas. As your earnings increase or debts clear, systematically boost your savings rate to accelerate financial independence and achieve your long-term goals. (Image: Canva)
The 50/30/20 rule provides a sustainable path to financial wellness by balancing current enjoyment with future security. By categorizing spending, automating savings, and adjusting ratios to your real-life needs, you can eliminate end-of-month financial stress and build lasting wealth. (Image: Canva)
Source link
[ad_3]
